Momentum Model: Harnessing the Power of Trends
Overview
FT Cloud's Momentum Model is a sophisticated tool designed for creating momentum-based trading systems. It draws on time-tested methods favored by active managers, encapsulated in the mantra: "buy the winners, sell the losers." By defining a specific universe of investments, applying a custom ranking algorithm, and selecting the top performers, this model enables users to strategically position their portfolios for potential gains.
Basics of Momentum Trading
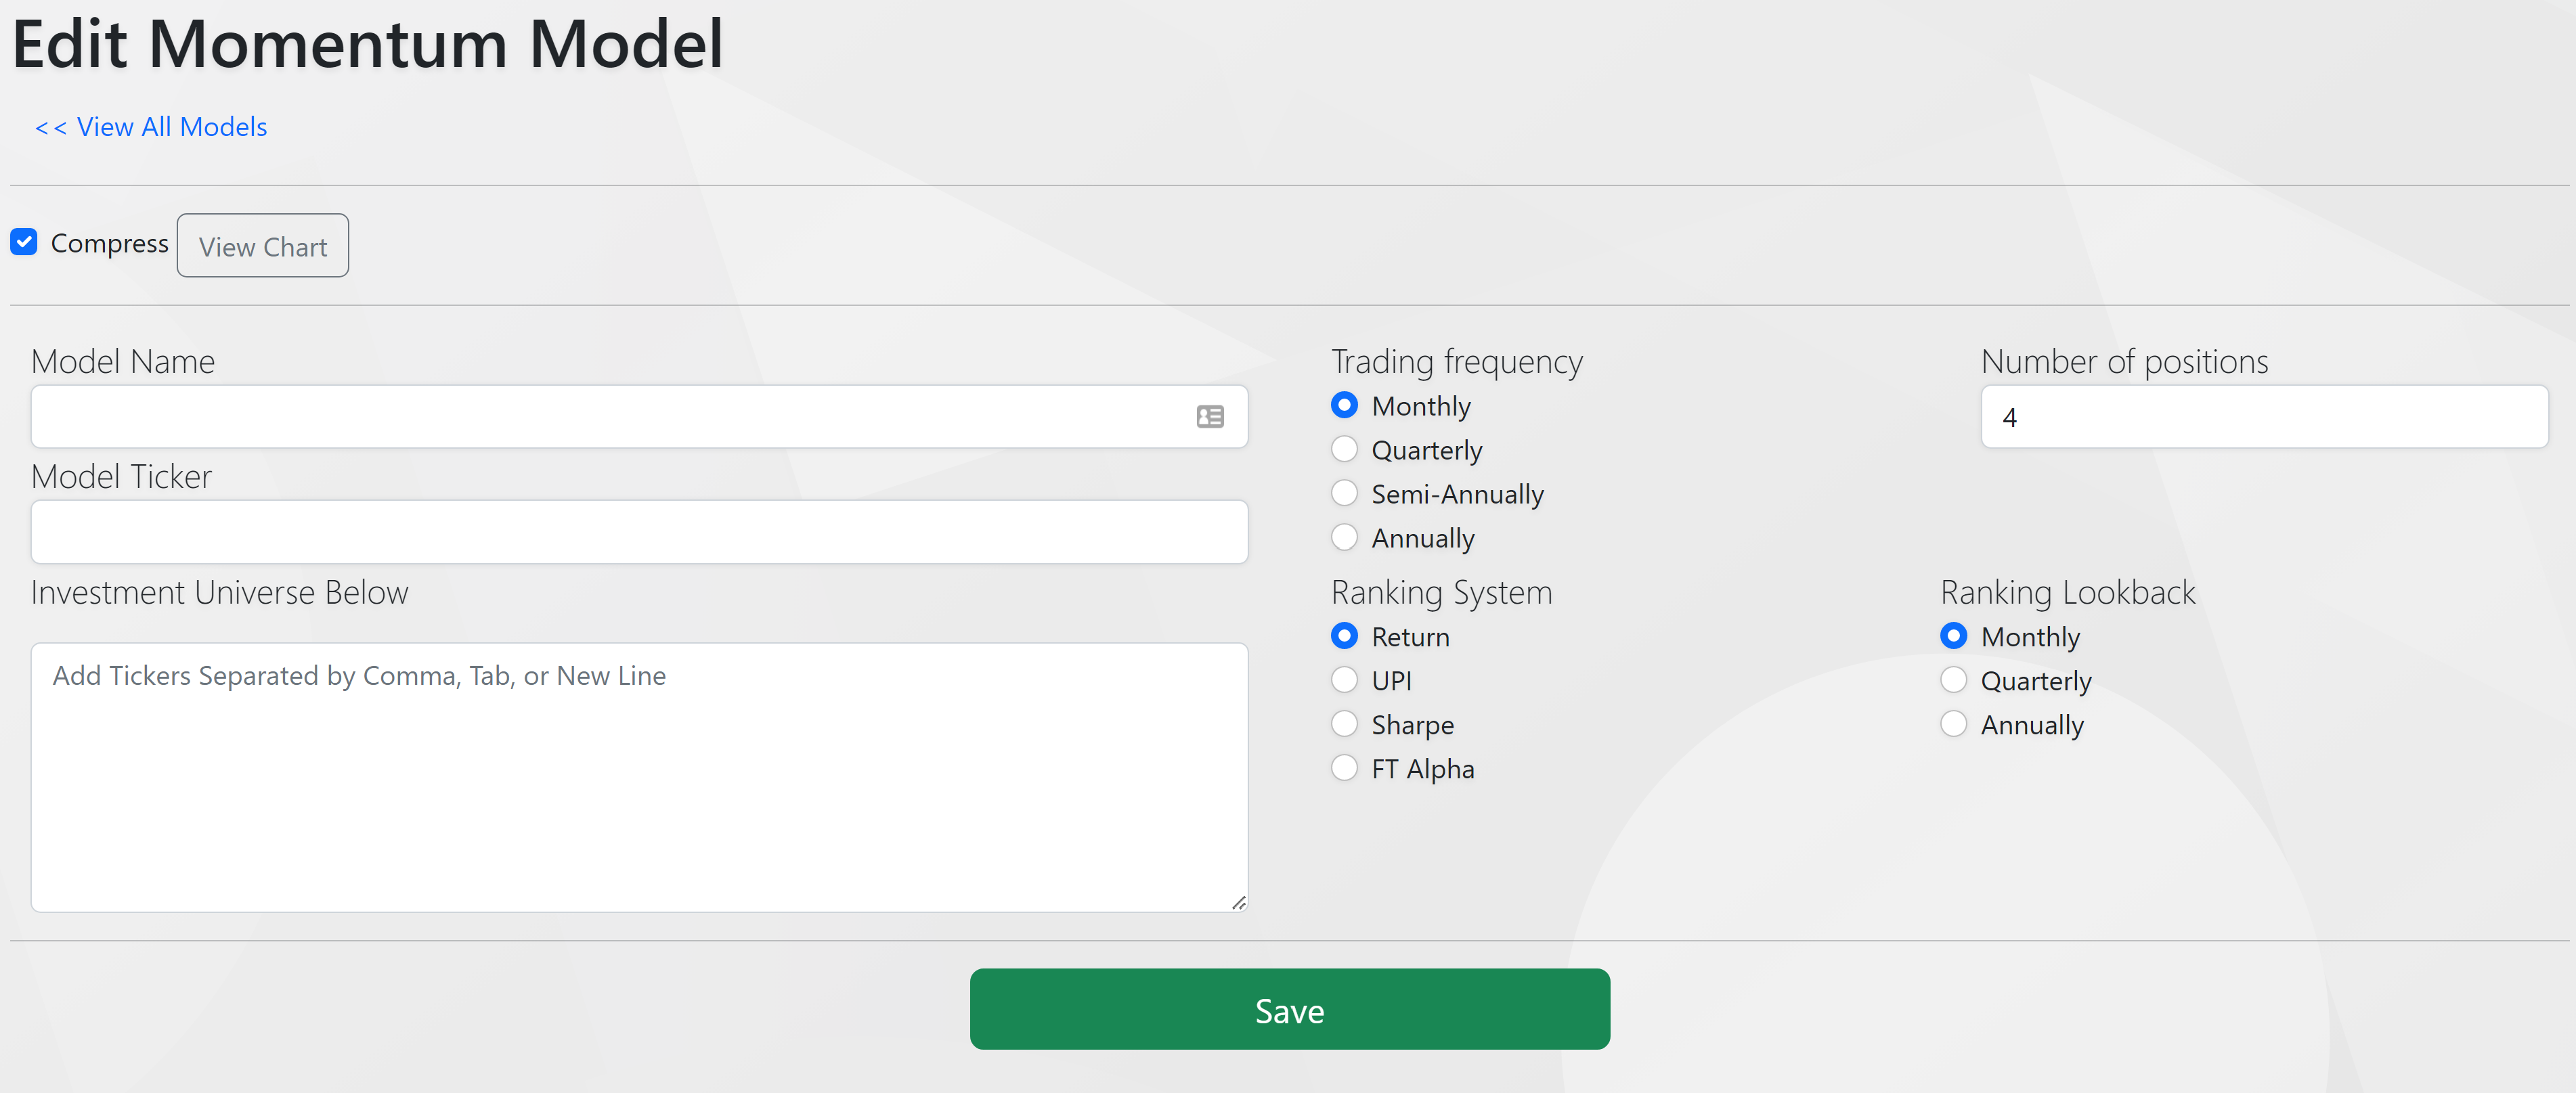
Leverage the following parameters and inputs to craft your trading strategy. FT Cloud facilitates rapid backtesting, presenting results through comprehensive charts, statistics, and performance metrics.
Investment Universe
Start by defining a broad or targeted group of securities for trading. Possible selections include, but are not limited to:
- Sector-specific securities (e.g., Sector SPDRs)
- Diversified bond funds
- Large cap stocks
- Customized lists of securities
Ranking System
The essence of momentum trading lies in identifying the BEST securities. Our platform provides a variety of metrics to rank your investment universe effectively:
- Return: Prioritize securities based on total return.
- UPI (Ulcer Performance Index): Consider both risk and return.
- Sharpe Ratio: A dual focus on risk and return.
- FT Alpha: A comprehensive measure that evaluates risk, return, and correlation.
Ranking Lookback Period
The lookback period is critical for determining how recent performance influences rankings. Options include:
- Monthly
- Quarterly
- Annually
- Additional granularity is available through our desktop software.
Trading Frequency
Determine how often the portfolio should be rebalanced:
- Monthly
- Quarterly
- Semi-annually
- Annually Our system ranks securities at each period's end, with trades executed on the next market day (T + 1).
Number of Positions
Specify how many securities your portfolio should hold at any rebalance. The investment universe is ranked, and the portfolio is then equally allocated among the top selections. For instance, selecting four positions means investing 25% of the portfolio in each of the top four ranked securities.
Application
Enhancing Diversified Portfolios
Integrate a momentum model into your equity strategy to potentially increase returns and reduce risk. Replace a static mix of 3-4 equity funds with a dynamic, momentum-based approach.
Optimizing Bond Portfolios
Rather than maintaining a diversified bond portfolio through a static selection of 5-6 funds, consider applying a momentum strategy to hold the top 2-3 funds, rebalancing quarterly. This approach aims to enhance returns while preserving diversification. Explore this strategy further through our tutorial: https://fasttrack.net/videos/#buyhold